
Hong Kong passes a law requiring crypto platforms to collect user tax data from 2027, with automatic exchange with other countries starting in 2028
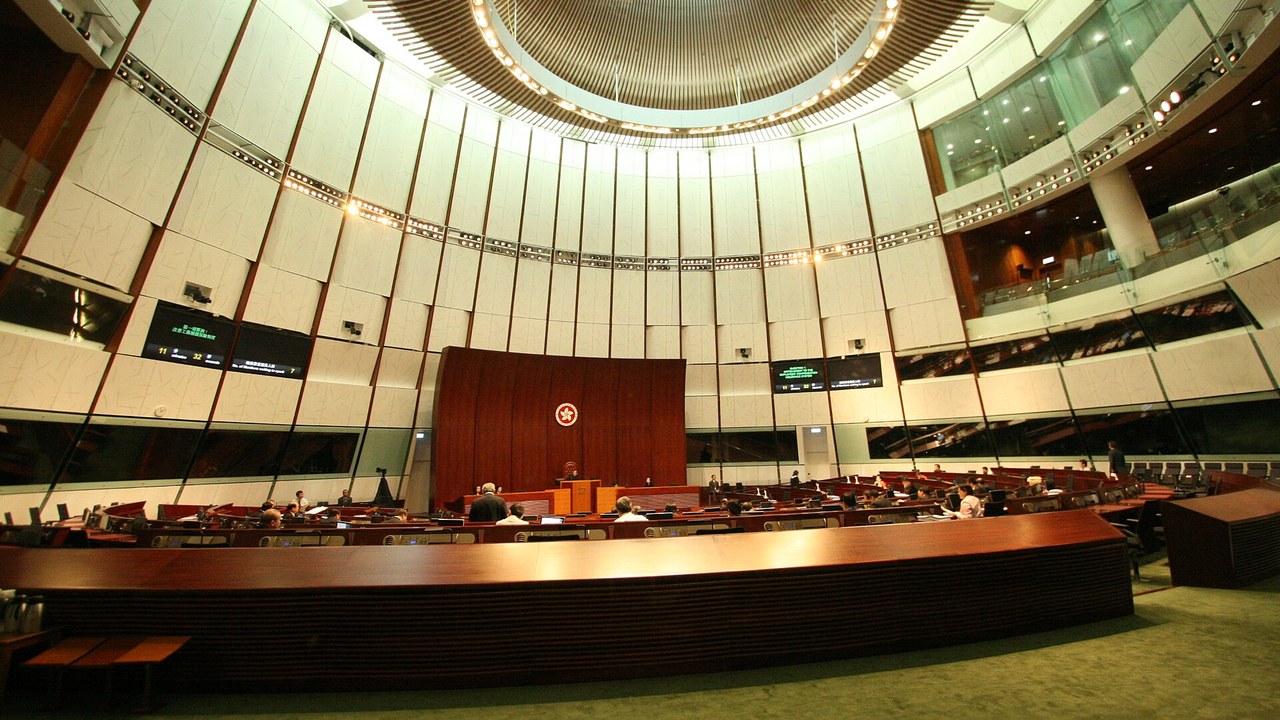
Hong Kong has written international crypto tax reporting into its own law. The Legislative Council passed the Inland Revenue (Amendment) (Crypto-Asset Reporting Framework and Amended Common Reporting Standard) Bill 2026 on Wednesday, the government said, at a meeting where the second reading debate was scheduled to resume at 11am, according to the council's notice.
The bill brings in the Crypto-Asset Reporting Framework, which the OECD published in 2023, along with recent amendments to the Common Reporting Standard. The government said the crypto framework takes effect in 2027, when relevant service providers must begin collecting the specified information. Automatic exchange of that information starts in 2028, the same year the amended standard takes effect, and the Inland Revenue Department begins exchanging financial account information under the amended standard in 2029.
Hong Kong has exchanged financial account information each year under the standard since 2018. The government said the new exchanges will be reciprocal, with suitable partner jurisdictions, and will protect confidentiality and data security. Christopher Hui, the secretary for financial services and the treasury, said Hong Kong "has been supporting international efforts in enhancing tax transparency and combatting cross-border tax evasion."
The Inland Revenue Department said it will issue guidance and has set up a dedicated team to give technical support and answer enquiries. For platforms, the next step is that guidance, ahead of the 2027 start.
This story is reporting and analysis. It is not financial, legal or tax advice.
- SanctionsThe EU launches a crypto task force against Russian sanctions evasion, planned to run 12 months at first, alongside a new Commission sanctions office
- South KoreaSeoul's finance minister proposes moving the crypto tax start to 2029 to wait for US data sharing, along with a three-year loss carry-forward
- BinanceBinance will close affected customer accounts on December 31, and users in France, Spain, Italy and Poland say emails warn of a monthly fee from November 29
- ParaguaySome Paraguayan sellers ask about 6% to 13% above the official dollar rate for USDT as the Ueno Bank collapse locks customers out of accounts